


Govern the Advice, Not the App
Aradhna Mangla is an AI & Data leader in Financial Services at EY, focused on helping wealth and asset managers move from...
Sep 11, 2026
Aradhna Mangla is an AI & Data leader in Financial Services at EY, focused on helping wealth and asset managers move from “AI pilots” to real, governed, scalable outcomes.
She is also the author of a new, independent research paper entitled “Responsible “Language” for Client Context (RLCC): Reducing Automation Bias and Temporal Unfairness in AI-Mediated Wealth Advice”. In this paper, Aradhna discusses two risks wealth management firms may be running when they begin using client data to generate advice summaries, planning narratives, and advisor prompts. The first is “automation bias” in which advisors accept on AI-generated narratives too readily. The second is “temporal unfairness,” in which AI systems built on historical behavioral patterns fail to anticipate or account for the flexibility clients need when conditions change.
Her paper introduces Responsible Language for Client Context (RLCC) as a workflow design intervention. RLCC does not require new models or new regulation. But it does require evidence-linked claims, explicit representation of contradictions, and automation throttling during instability windows.
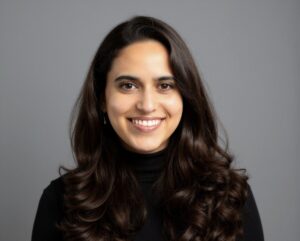
Aradhna is hosting a lunch-time session on this topic called Govern the Advice, Not the App: AI Governance in Wealth Management at noon on September 24 during Boston Fintech Week. During this free, hour-long session, she will lead a discussion of AI governance as it applies to wealth management.
RSVP here: https://luma.com/cc7siy7z (advance reservation required)
Aradhna, what interested you in the concept of client context as language?
Client context is the best approximation of the clients any wealth manager may advise. What we ‘think’ of as a client – is actually what we store in our systems as Client Data. Often times, this data has aged since the time the client onboarded and the nuances of the client and their household’s life is something that an Advisor can perceive during their check-ins. However, new information may not be complete, or added to the client profile that advice is generated for. This led me to think about how a client’s context is a type of living, breathing language. We start with 30-40 words on the client and create their ‘profile’ (e.g., “55-year-old married male, two dependents, moderate risk tolerance, $1.2M in assets, retirement in 10 years, employed in tech, primary goal capital growth”) – and over the course of the advisory relationship we expand that language and grow it to 100-300 words (e.g., adding “recently widowed, now sole caregiver for an aging parent, took early retirement package, shifted from growth to capital preservation, funding a grandchild’s education, liquidity needs increased after a home purchase, more conservative after market volatility, expressed interest in charitable giving and estate planning”). This is the language and context that downstream systems and users use to communicate about the client.
One of the risks you identify as being under examined in the use of AI in wealth management is “automation bias”. This isn’t new, is it? It’s well documented in other areas and can occur independently from AI.
Exactly! Automation Bias isn’t new as a concept. But AI in Wealth Management, and specifically AI – generated Financial Advice is a new concept. 20 years ago, you couldn’t dream of handing over your intimate household details to a chatbot. But now, it’s expected. Many firms are launching Agentic Financial Advisors too. As the industry shifts towards efficiencies, I think this is where the unknowns like automation bias to real damage.
The danger isn’t that the model’s math is wrong, it’s that the language is thin or stale and still reads as complete. When a client’s context is still the 30-40 word version (“moderate risk, growth objective, retirement in 10 years”) but their life has moved to the 100-300 word reality (“recently widowed, now a caregiver, shifted to preservation, liquidity needs rising”), the AI still generates a fluent, confident narrative from the outdated words. The advisor reads it, it sounds right, and it becomes an invisible anchor. Nobody challenges it, because nothing signals the language is out of date.
Put that in an Agentic Advice workflow, and the risks compound.
A second risk which you identify is “temporal unfairness”. This is particularly interesting because it can be counter intuitive. As a compliance professional in wealth management, you probably want your AI models to treat people who are otherwise alike in a similar fashion across demographic groups. But you make the point in your paper that this can disadvantage some clients when things in their lives go wrong.
Thank you for this question, Jim 😊
We’re in the business of advising humans. And humans change. Now putting this into a data context – what a wealth management firm stores as ‘client context’ isn’t fixed, it moves. The unfairness I worry about isn’t across demographic groups, it’s across time, within the same person and their household. We segment people according to their demographics in broad strokes – HENRYs, HNWs, FIRErs. But our story about money is so personal, so diverse. Our life experiences color our relationship with money. When faced with positive and negative life events (birth of a child vs. loss of employment), humans are known to have rich and diverse responses. Within the same demographic, a positive life event may cause strife (unexpected child care costs causing credit card debt), and a negative life event may cause a pivot (change from traditional employment to owning small businesses) – which may or may not reflect in the advisory relationship on time.
Now run this through an AI advice workflow. The model treats two clients who look alike in the data the same way, but one of them has actually moved into a hardship window that the stored language hasn’t caught up to yet. That’s temporal unfairness. The system becomes least flexible at exactly the moment a client needs the most human discretion, and the needs of an individual get hidden because the numbers still look fair in the aggregate. The clients it disadvantages most are the ones going through the hardest chapters of their lives, which is precisely where stale language and automation bias compound. So fairness can’t just mean treating alike clients alike, it has to mean treating temporary hardship as context rather than deterioration, and testing for it across time and life stage, not at a single point in time.
Can you say a bit about the three governance frameworks that currently dominate AI risk management in wealth management?
Most firms align with the NIST AI Risk Management Framework as the US backbone. It’s Govern, Map, Measure, Manage functions give firms a shared language for AI risk, now extended for our sector through the FS AI RMF. ISO/IEC 42001 is the international, certifiable management-system standard, the “how you run AI governance as an ongoing program” layer. And the EU AI Act is the hard-law, risk-tiered regulation that’s fast becoming the global benchmark firms design to. They’re all necessary, but they mostly govern the AI model. None of them are tailored to financial advice and adopted across the industry. Each Wealth management firm finetunes their AI governance and guardrails based on their own data (client context), and risk measures (risk of wrongdoing, reputational harm, client harm, etc.). So a universal standard is missing, particularly in Wealth and Asset Management.
What is Responsible Language for Client Context (RLCC)?
RLCC is my framework for bridging the key gaps the NIST RMF, ISO/IEC 42001, and the EU AI Act leave space for. How about we start governing the two blind spots those three miss? Firms can control how the client is represented as language before the model, and how that language is consumed after it.
By adopting the RLCC framework – we can control for ‘Representation risk’ i.e., whether client context was translated completely and fairly, and ‘Consumption risk’ i.e., whether the advisor actually challenged, sourced, and documented the output.
Due to a lack of WAM specific standards, RLCC is built to create advisory processes that are auditable, not aspirational, with real metrics: context completeness, source traceability, life-event sensitivity, advisor challenge rates, and stress-window testing. In short, it makes the living language of the client a governed asset, with the final advice decision kept in check by a human.
Who is your lunch session designed for? Who do you hope to see in the room?
My session is built for the people who live in Wealth and Asset Management, and design the systems behind it. This session is of interest to chief compliance officers, heads of supervision, risk and legal leaders, and chief data and AI officers in the room, alongside the product and technology leaders actually shipping advisor copilots and agentic advice. My hope is simple: that anyone who’s been trying to govern AI at the 10,000 ft level of Enterprise Policies (word documents), or Workflow tools, leaves realizing the real unit of supervision is at 10ft i.e. the advice itself. If a compliance leader walks out able to ask their Product and Data teams “was this client represented, and consumed, responsibly,” and what are the metrics that answer it, the session did its job.
# # #

Aradhna Mangla is an AI & Data leader in Financial Services at EY, focused on helping wealth and asset managers move from...

We had many distinguished, accomplished, fascinating speakers at Boston Fintech Week in September, but perhaps none attracted as much attention as Alexander...
The Fintech 5 is a series of blog posts consisting of questions and answers designed to help you get to know the...